
You’ve made an offer, negotiated the details, and signed the contract. Then your lender tells you it’s time for the appraisal.
For many buyers, this is one of those parts of the home-buying process that happens mostly behind the scenes. Sellers may have questions, too. Who chooses the appraiser? What are they actually looking at? And what happens if the home doesn’t appraise for the agreed-upon purchase price?
If you’re buying or selling a home in Montgomery County, understanding the home appraisal process before you reach this stage can make the experience a lot less intimidating.
What Is a Home Appraisal?
A home appraisal is an independent professional opinion of a property’s value. According to the Consumer Financial Protection Bureau, an appraisal provides information about a property, what contributes to its value, and how it compares with other properties in the area.
When you’re financing a home purchase, the appraisal helps your lender determine whether the home’s value supports the amount being financed. In other words, it isn’t about whether you love the house enough to pay the purchase price (or whether the seller believes it’s worth every penny). It gives the lender an independent opinion of the property’s market value.
It’s also important to understand that an appraisal and a home inspection are two different things (and both are important parts of the home-buying process). While an appraiser is focused primarily on value, a home inspector takes a much closer look at the condition of the property and its major systems and components. An appraisal can tell you what a home is worth, but it isn’t a substitute for understanding the condition of the home you’re buying.
How Does a Home Appraisal Work?
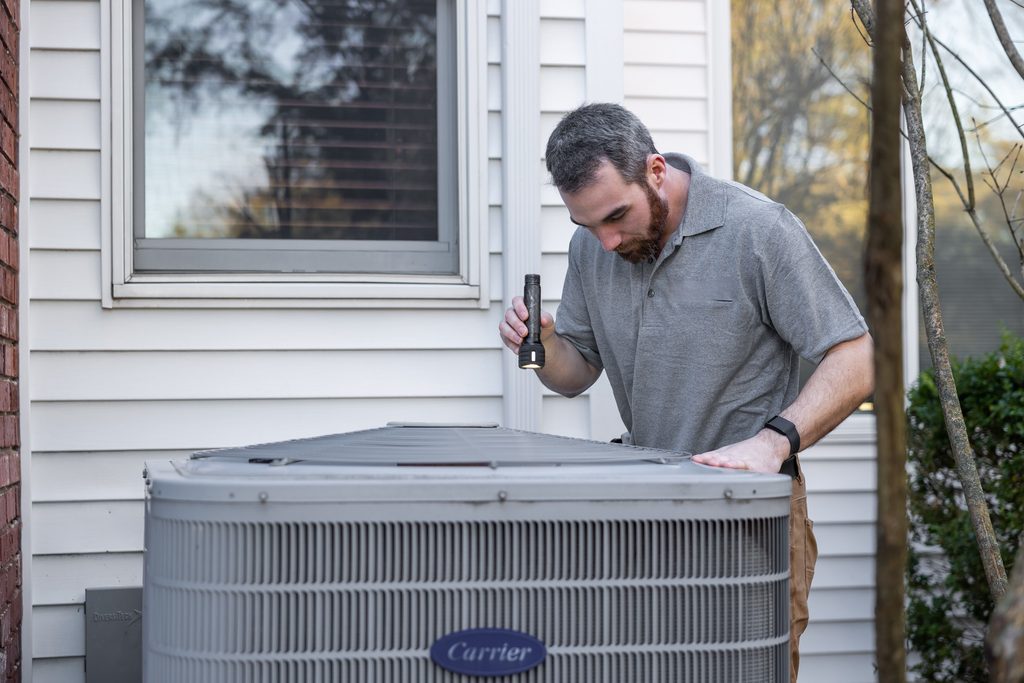
Once you’re under contract and your financing is moving forward, your lender will typically order the appraisal. From there, an independent appraiser evaluates the home and researches the surrounding market before preparing a report with an opinion of the property’s value.
Here’s a closer look at what buyers and sellers can expect during the home appraisal process in Montgomery County.
Who Chooses the Home Appraiser?
If you’re the buyer, you generally don’t choose your own appraiser. Neither does the seller or either real estate agent.
The lender is responsible for arranging the appraisal and selecting a qualified appraiser, either directly or through an appraisal management company. Fannie Mae’s Appraiser Independence Requirements are designed to keep the appraisal process independent and prevent anyone with an interest in the transaction from improperly influencing the appraiser or the final value.
So while you may be the one paying for the appraisal, you won’t be scrolling through reviews and choosing an appraiser yourself. Your lender handles that part for you.
How Much Does a Home Appraisal Cost?
The cost of a home appraisal varies depending on the property, location, complexity of the appraisal, and other factors. A large acreage property or a particularly unique home, for example, may require more work to appraise than a home in a neighborhood with plenty of recent comparable sales.
According to Angi’s 2026 Houston home appraisal cost data, a home appraisal in Houston costs $452 on average, with typical costs ranging from $364 to $540.
In a typical financed purchase, the buyer pays the appraisal fee even though the lender orders it. You should see the appraisal charge included with the other loan costs provided by your lender.
The appraisal is just one of several expenses to plan for when purchasing a home. If you’re preparing your budget, I break down the additional costs to expect when buying a home in Montgomery County in this guide.
What Does the Appraiser Look For?
This is where the process gets a little more interesting.
The appraiser evaluates the property and compares it with the surrounding real estate market. According to Fannie Mae’s guide to home appraisals, factors that can affect value include the home’s size and design, square footage, number of bedrooms and bathrooms, condition, location, property features, comparable sales, and current market trends.
Those comparable sales, or “comps,” are an important piece of the puzzle. The appraiser looks for recently sold properties that are reasonably similar to the home and considers relevant differences between them.
And around Montgomery County, there can be plenty of differences to consider.
A home on acreage in Magnolia isn’t necessarily comparable to a similarly sized home in a master-planned community. A waterfront property in Montgomery brings something entirely different to the table. Pools, workshops and outbuildings, renovations, lot size, neighborhood amenities, and other features can all help distinguish one property from another.
This is also where working with a real estate professional before you reach the appraisal can make a big difference.
For sellers, pricing your home effectively from the beginning means looking beyond what you hope to get for it and understanding what comparable properties are actually selling for in your part of Montgomery County. For buyers, understanding the local market can help you focus your time and energy on homes that are priced realistically and make an informed offer when you find the right one.
An appraisal is still an independent opinion, and no Realtor can guarantee where that number will land. But starting with a price and offer strategy grounded in real market data can help both buyers and sellers head into the appraisal with fewer surprises.
What Happens After the Home Appraisal?
And now for the part everyone really wants to know: What did it appraise for?
The appraised value will generally land in one of three places—at the purchase price, above it, or below it. What happens next depends on that result, and it can look a little different depending on whether you’re buying or selling.
If the Home Appraises at the Purchase Price
This is typically the simplest outcome.
For the buyer: The lender now has an independent valuation supporting the price you agreed to pay. Assuming the rest of your financing is on track, you can continue moving toward closing without an appraisal gap to address.
For the seller: There generally isn’t anything else to negotiate based on the appraisal itself. You keep moving through the remaining steps toward closing.
It may not be the most exciting news you’ll get during a home purchase, but sometimes boring is exactly what we want!
If the Home Appraises Above the Purchase Price
Say you’re under contract for $425,000 and the appraisal comes back at $440,000. Great news, but what does that actually change?
For the buyer: You still purchase the home for the price established in your contract. The seller doesn’t automatically get to increase the purchase price because the appraisal came in higher. It’s certainly an encouraging result, but I also wouldn’t think of that $15,000 difference as guaranteed equity. An appraisal is an opinion of the home’s value at a particular point in time, and real estate values can change.
For the seller: The higher appraisal doesn’t automatically change your contract price either. If you agreed to sell for $425,000, an appraisal of $440,000 doesn’t mean the buyer now owes you an additional $15,000.
It’s easy to see that number and wonder whether you could have sold for more, but remember that the appraisal is only one piece of the transaction. Your negotiated price reflects the market, buyer demand, property condition, terms of the offer, and other factors that were in play when you went under contract.
If the Home Appraises Below the Purchase Price
This is the scenario that tends to cause the most stress—but a low appraisal doesn’t automatically mean the sale is over.
Let’s say the purchase price is $450,000 and the home appraises for $430,000. You now have a $20,000 appraisal gap, and that can affect the buyer’s financing.
For the buyer: Your lender is making its lending decision based in part on the property’s appraised value, so you may need to decide how you want to address the difference. Depending on your financing and the terms of your contract, that could mean renegotiating the purchase price, bringing additional cash to closing to cover some or all of the gap, or finding another solution with the seller.
If you believe the appraisal contains an error or important information was overlooked, there may also be an opportunity to request a reconsideration of value through your lender. Fannie Mae provides more information about reconsiderations of value and when a borrower may question an appraisal.
For the seller: A low appraisal doesn’t automatically require you to reduce your price. However, if your buyer is financing the purchase, the lower valuation may make it difficult for them to proceed under the original terms. You may be asked to lower the price, meet the buyer somewhere in the middle, or consider another solution.
Whether a buyer can terminate because of a low appraisal also depends on the specific terms of the contract. This is one of those moments when I don’t recommend relying on what happened when your neighbor sold their house or what someone told you they did five years ago. Your contract, financing, appraisal gap, and circumstances all matter.
A low appraisal can feel like a big roadblock when that number first comes in, but it doesn’t always have to be the end of the transaction. The next step is understanding the options available to you and deciding which one makes the most sense.
Looking for a Trusted Mortgage Lender in Montgomery County?
Your lender plays a big role in the home-buying process, from helping you understand your financing options and getting preapproved to ordering the appraisal and keeping your loan moving toward closing. Having someone you trust on that side of the transaction can make the process feel a whole lot easier.
If you haven’t chosen a mortgage lender yet, I’m happy to connect you with local professionals I know and trust. You are always free to choose the lender that’s right for you, but if you aren’t sure where to start, here are a few Montgomery County mortgage lenders I recommend:
Adam Simmons, Crystal Clear Mortgage
crystalclearmortgage.com
Charles Goodwin, K&G Capital
kgcm.com
Rich Sproba, CMG Home Loans
Rich Sproba – CMG Home Loans
Buy or Sell With Confidence in Montgomery County, TX
The appraisal may happen behind the scenes, but the decisions leading up to it matter. Pricing a home correctly, understanding comparable sales, recognizing what makes a property stand out, and knowing how to respond when the numbers don’t come back exactly as expected can all make a difference in a successful transaction.
That’s where having an experienced local Realtor on your side matters.
I’m Nicole, owner of Clearview Real Estate, and I help buyers and sellers throughout Montgomery County make informed real estate decisions based on what’s actually happening in our local market. For sellers, that means developing a pricing and marketing strategy designed to position your home well from the start. For buyers, it means helping you recognize value, focus on homes that make sense for your goals and budget, and put together a competitive offer without losing sight of the numbers.
And if an appraisal does bring an unexpected result? You won’t be left trying to figure out your options on your own.
Whether you’re buying or selling in Conroe, Montgomery, Magnolia, Willis, or elsewhere in Montgomery County, contact me and let’s talk about your next move.
Leave a Reply